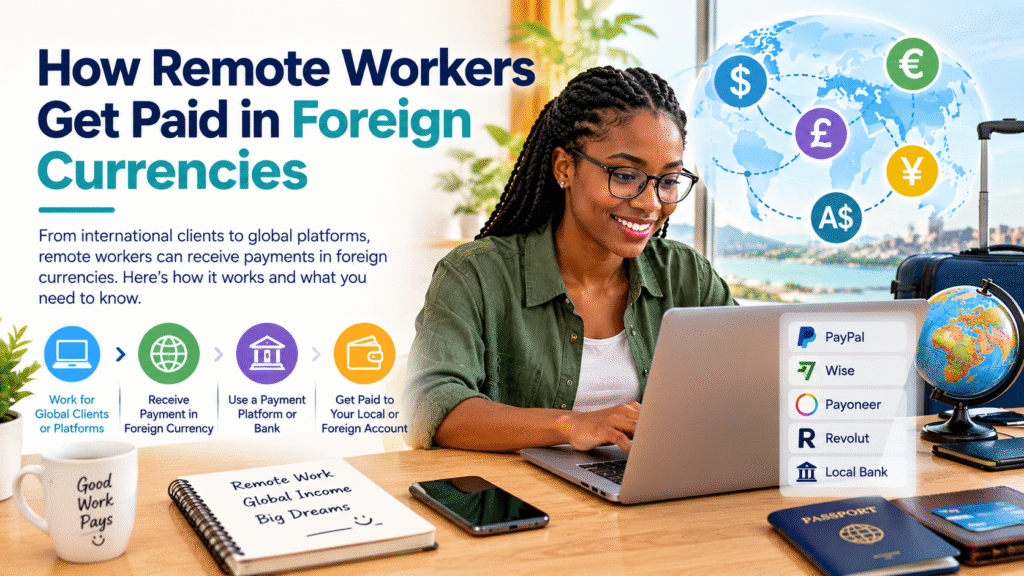
Remote work has made it possible to earn money from clients and companies in other countries. A designer in Nigeria may work for a company in the United States. A developer in Canada may receive payments from a client in Europe. A virtual assistant in the Philippines may be paid by a business in Australia.
International work creates more opportunities, but it also introduces a question that local workers do not usually face: how much will the payment actually be worth after currency conversion?
How international payments work
A remote worker is usually paid in the currency selected by the employer, client, or freelance platform. The payment may arrive in US dollars, euros, pounds, Australian dollars, or another currency.
The worker then receives the money in one of three common ways:
- Directly into a foreign-currency account
- Through a payment platform that converts the money automatically
- Into a local bank account after the payment provider applies an exchange rate
The amount received in the local currency depends on the exchange rate used, the timing of the conversion, and any transaction fees.
Why the exchange rate matters
Suppose a remote worker earns USD 1,000 and converts it to their local currency. The final amount depends on the USD exchange rate at the time of conversion.
If the exchange rate changes before the money is converted, the local-currency value may rise or fall. This is why two workers receiving the same foreign-currency salary can receive different local amounts if they convert their money on different days or use different providers.
The rate shown on a currency converter is usually a reference rate. A bank or payment provider may use a slightly different rate after adding a spread or markup.
Fees that can reduce a remote worker’s earnings
Exchange-rate differences are not the only cost. International workers should also check for:
Transfer fees
Some platforms charge a fixed fee for sending or receiving money. Others charge a percentage of the transaction.
Currency-conversion markups
A provider may advertise a low or zero transfer fee while using an exchange rate that is less favorable than the mid-market rate. The difference between the reference rate and the provider’s rate is an indirect cost.
Withdrawal fees
Freelance platforms and payment services may charge a fee when money is withdrawn to a bank account or card.
Minimum and maximum limits
Some services limit how much can be transferred or withdrawn at one time. This can affect workers who receive large monthly payments.
How remote workers can compare payment options
Start by comparing the final amount received, not only the advertised fee. A service with a small transfer fee may still be more expensive if its exchange rate is poor.
Before accepting a payment method, check:
- The currency in which the client will pay
- The rate used for conversion
- All fixed and percentage fees
- The expected delivery time
- Whether the payment can remain in the original currency
- Whether tax or reporting obligations apply in your country
Use the Currency Switch Now converter to estimate the reference value of the payment before converting it through a bank or payment platform.
Should remote workers keep money in a foreign currency?
Keeping part of an income in a foreign currency may be useful when a worker regularly pays for services, subscriptions, travel, or business expenses in that currency. It can also reduce the need for repeated conversions.
However, holding foreign currency also creates exchange-rate risk. If the foreign currency loses value against the worker’s local currency, the local value of the savings may decrease.
The best decision depends on cash-flow needs, fees, local regulations, and how soon the money will be spent.
Frequently asked questions
Are remote workers always paid in the client’s currency?
No. The payment currency depends on the client, contract, freelance platform, and payment method. Some clients pay in their local currency, while others agree to pay in the worker’s currency.
Why is the amount I receive different from the converter result?
A converter often shows a reference or mid-market rate. Your bank or payment provider may apply a markup, service fee, or different settlement rate.
Is it better to convert immediately?
Not always. Converting immediately can make budgeting easier, but waiting may result in a better or worse rate. Avoid treating exchange-rate movements as predictable.
Can remote workers be paid through more than one currency account?
Some financial services allow users to receive and hold several currencies. Availability depends on the provider, country, account type, and applicable regulations.
Final thoughts
Foreign-currency payments can expand a remote worker’s opportunities, but the headline payment is not always the amount that reaches a local bank account. Exchange rates, conversion markups, transfer fees, and withdrawal charges all affect the final value.
Compare the reference value first, understand the provider’s full cost, and keep records of international income and payments. Use Currency Switch Now to check current currency values before making conversion decisions.
Currency Switch Now provides currency information and conversion tools. It is not a financial advisor. Exchange rates fluctuate, so verify the latest rate before making financial decisions.